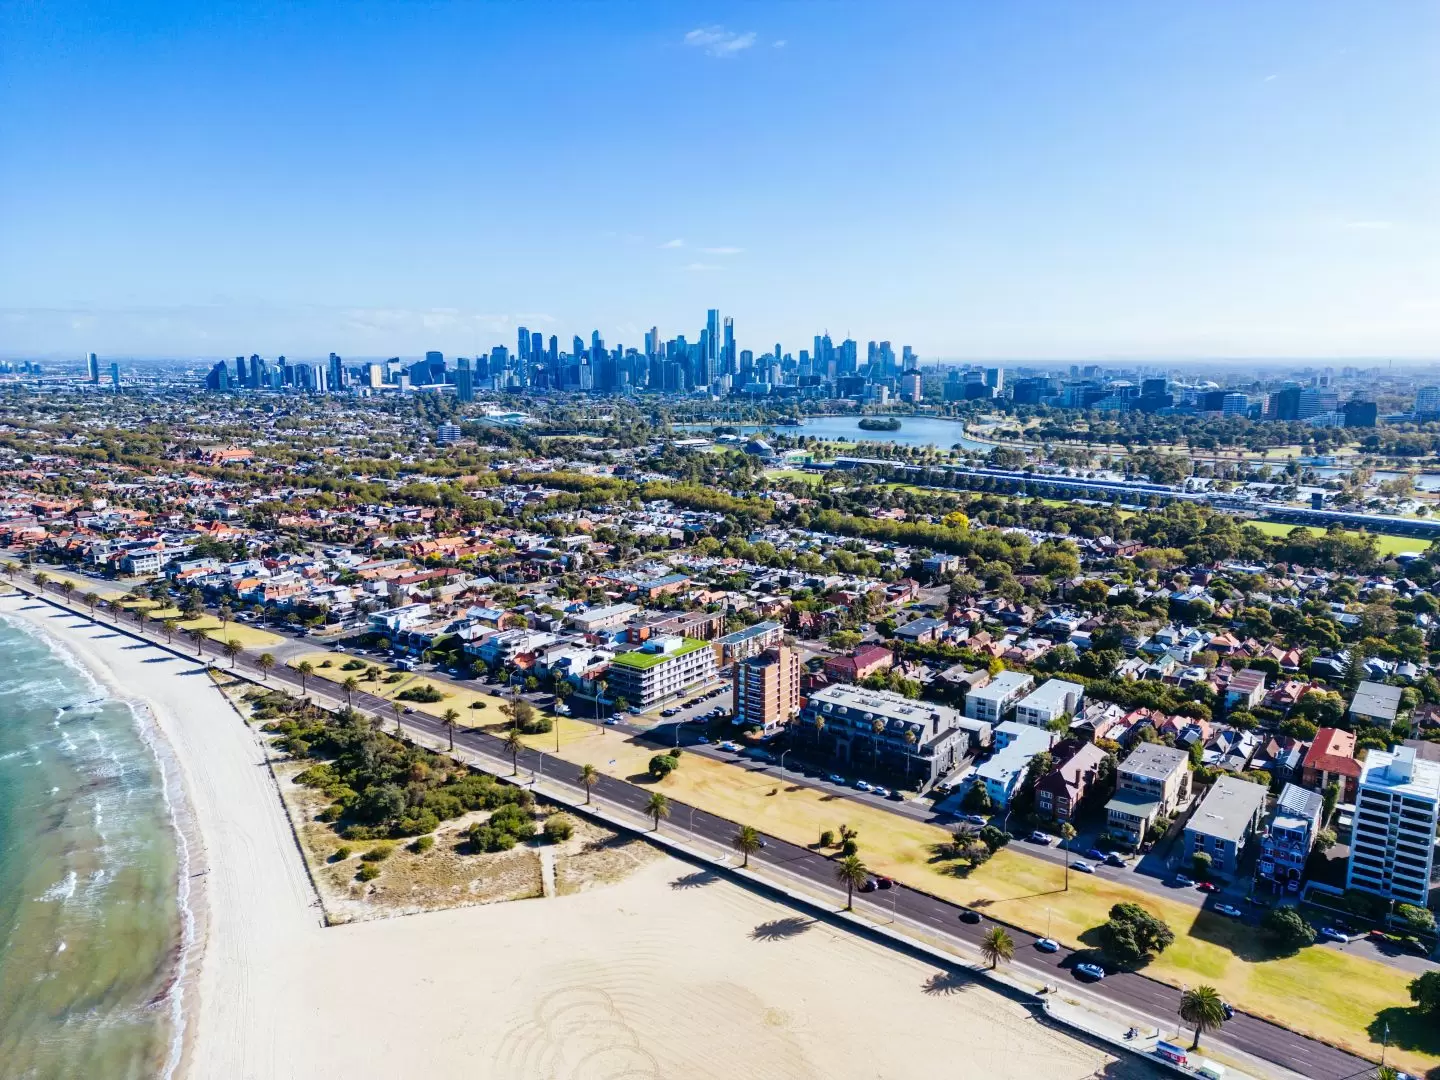
So while Melbourne property prices have been fading off a low base for the past few months, there is another side to that story for investors.
Cotality’s September Home Value Index showed Melbourne now has a gross dwelling rental yield of 4.0% – higher than Sydney, Brisbane, Adelaide and Perth.
That doesn’t automatically make Melbourne a leading investment. But it might change the numbers for investors who have spent the past few years watching prices rise much faster in other capitals.
The combination of lower purchase prices and rising rents means Melbourne investors are now getting more rental income relative to the price they pay for a property.
So is Melbourne’s downturn creating an opportunity?
This article is general information only and does not constitute financial, legal or tax advice. We recommend seeking advice from a qualified accountant and solicitor before making any decisions.
Melbourne’s rental yield has moved ahead of the other major capitals
According to Cotality, Melbourne’s gross dwelling rental yield reached 4.0% in August.
That compares with:
- Perth – 3.9%
- Adelaide – 3.6%
- Brisbane – 3.4%
- Sydney – 3.3%
When broken down by property type, Melbourne really shines, with units producing an even higher gross yield of 5.1%, compared with 3.5% for houses.

The shift has happened partly because the two sides of the yield equation have been moving in opposite directions. Melbourne dwelling values fell 4.7% over the 12 months to August. At $786,718, the city’s median dwelling value is now 6.8% below its peak.
Rents, meanwhile, have continued to rise. Cotality recorded Melbourne house rents rising 5.1% over the year to August, while unit rents increased 4.9%.

When the amount investors pay for a property falls while the rent it can generate rises, gross rental yields improve.
Why does a higher rental yield matter for investors?
Gross rental yield measures annual rental income as a percentage of a property’s value. For an investor, a higher yield can mean more rental income relative to the amount invested in the property. That can help with the ongoing cost of holding an investment, particularly when mortgage rates remain high.
But a 4.0% gross yield should not be confused with a 4.0% return in your pocket. Gross yield is calculated before expenses. You still need to allow for interest, property management fees, maintenance, insurance, council rates, land tax where applicable and periods when the property may be vacant.
According to Cotality, gross yields across the larger capitals are currently below the level generally required for a neutral cash flow position while interest rates remain elevated.
So Melbourne’s improving yield is important because the equation has become more favourable – not because the average investment property has suddenly become cash-flow positive.
Rental demand is still supporting the numbers
None of this works if tenants are not there to pay the rent. But Melbourne’s rental market remains relatively tight.
According to SQM Research, Melbourne’s rental vacancy rate was 1.8% in July 2026. While that is higher than the exceptionally low vacancy rates recorded in 2023 and 2024, the longer-term data show rental availability remains relatively constrained. It is also still below the 2-3% commonly considered a balanced market.

That means Melbourne’s improving yields are being supported by more than falling property prices. With low rental availability, there is sustained upward pressure on rental rates, which is important for investors relying on consistent rental income.
Of course, a city-wide vacancy rate can only tell you so much. Conditions can vary considerably between suburbs and property types, so you still need to assess the rental demand for the particular property and location you are considering.
Falling prices are the other half of the equation
Rental demand explains why the income side of the equation has held up. But Melbourne’s improving yields are also being driven by what has happened on the other side: the price investors are paying to buy property.
Melbourne’s market is in a downturn. Dwelling values are down 6.8% from their March 2022 peak, while Cotality estimates Melbourne values have actually fallen 3.9% over the past five years.
Compare that with five-year growth of more than 60% in Brisbane and Adelaide and almost 80% in Perth.
For existing Melbourne homeowners, those numbers haven’t been particularly exciting. For a prospective investor, though, they can create a different starting point.
Lower prices can mean a smaller deposit, lower borrowing requirements and potentially less interest than buying an equivalent property at a higher price. Combine that with rents that have continued to rise and the income-to-purchase-price equation starts looking more attractive.
Do the numbers stack up for you?
A better yield changes the shape of an investment decision, but it does not remove the need to run your own numbers. Two Melbourne properties with the same purchase price can produce very different investment outcomes depending on the rent, property type, suburb, ongoing costs and potential vacancy.
And your finance is just as important. Your borrowing capacity, your existing loan structure and your income all determine whether a given yield and price combination actually works for your situation.
That is why a headline rental yield shouldn't be looked at in isolation. Before buying, work out what the property is realistically likely to earn, what it will cost you to hold and how the loan would fit alongside your existing financial commitments.
At AXTON Finance, we work with a panel of more than 30 lenders, which means we can model a specific Melbourne property against your servicing capacity, your deposit and your goals, rather than relying on a general yield figure. What looks attractive on a spreadsheet needs to hold up against your actual borrowing position, and that is a conversation you should have with an experienced broker before you commit to a purchase.
This article is general information only and does not constitute financial, legal or tax advice. We recommend seeking advice from a qualified accountant and solicitor before making any decisions.
Considering an investment property in Melbourne? AXTON Finance can help you understand your borrowing capacity and compare finance options for the property you’re considering. Call 03 9939 7576, email getabetterrate@axtonfinance.com.au or get in touch today.